How one W2 client plans to add $43,500 to his net worth in a year
Preston Seo · 6:41 ·
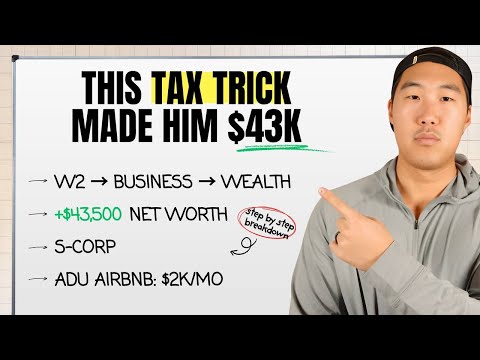
Summary
Preston walks through the plan his team built for a client he calls Mark, to protect his privacy. Mark earns roughly $140,000 a year from a W2 job and has about $8,000 a month in surplus cash flow. His goals are to lower taxes, build a second income stream, buy real estate and Bitcoin, and protect his wealth.
The plan has five steps. First, Mark activates his idle LLC with a business bank account, an accountable plan, and the Augusta rule, with an S corp election once profit passes $40,000. Second, he launches two to three Airbnb arbitrage units, with a projected $1,200 to $2,400 a month in net profit per unit. Third, he opens a solo 401k, does a backdoor Roth IRA each year, and puts 80% of investable capital in Bitcoin and 20% in index fund ETFs. Fourth, he turns his basement into an ADU for short-term rental. Fifth, he adds a revocable living trust, a $2 million umbrella policy, and series LLCs. Preston adds up the projected year one result to $43,500.
Key points
- Mark opens a business bank account so every dollar in or out of his LLC goes through one place.
- An accountable plan lets his LLC reimburse him tax free for costs like home office, internet, phone, and mileage, worth about $2,000 a year.
- Under the Augusta rule, the LLC rents his home for 14 days a year for business use at about $500 a day, which is $7,000.
- Once the LLC shows $40,000 or more in profit, the plan is to file Form 2553 and elect S corp status, saving about $6,000 in payroll tax.
- Each Airbnb arbitrage unit costs about 6 to 7 thousand dollars to set up and is projected to make $1,200 to $2,400 a month in net profit.
- Mark plans to borrow $25,000 from his HELOC to turn his basement into an ADU, which is projected to net $1,500 to $2,000 a month.
- His asset protection plan includes a revocable living trust, a $2 million umbrella policy, and a separate LLC for each future property.
- The projected year one total of $43,500 includes $6,000 in S corp savings, $12,000 in solo 401k deductions, and a $7,500 ADU refund.
Chapters
- 0:00Intro
- 1:09Step 1: Activating the LLC
- 2:44Step 2: Airbnb arbitrage for cash flow
- 3:36Step 3: Retirement planning and Bitcoin
- 4:30Step 4: House hack with an ADU
- 5:12Step 5: Asset protection
- 5:35Timing and execution
Read the guide
Transcript
Show the full transcript
0:00 Imagine adding more than $43,000 to your net worth this year without switching jobs, without gambling on crypto moonshots, and without sacrificing your lifestyle. One of our clients did just that. And today, I'm going to walk you through exactly how we did it step by step. So that way you can see what's possible when you use the system the way it was actually written. If this is your first time here, my name is Preston. I help busy professionals legally reduce taxes, grow their cash flow, and build wealth faster using a combination of smart structuring, automation, and intentional investing. Most people get stuck in the earn, get taxed, and then spend cycle. My clients, we flip it into earn, invest, and then optimize, and then tax. The story is one of the best examples of how that flip works in real life. Now, for the sake of privacy, we're going to call this client Mark. Mark earns roughly $140,000 per year from a stable W2 position, his household expenses are solid, and after taxes and also bills, he's consistently has about $8,000 per month in surplus cash flow.
0:50 Now, Mark came to us because his goals were simple but ambitious. First, he wanted to reduce his tax bill. Number two, he wanted to build a second income stream through his business. Number three, he wanted to start stacking real estate in Bitcoin. And number four, he wanted to protect his wealth from liability and probate. His entire plan is built around hitting all four goals. And we designed it to be manageable for someone working full-time. The first thing that we did was turn that idol LLC that he had into a functional business entity. And here's why that matters. Because first, most employees only get access to tax strategies at the very end after they've earned and been taxed. But once you have a business, you start to unlock a completely different set of rules. We walk Mark through a checklist to activate the LLC. We first opened up a business bank account. Every single dollar in or out goes through this account. So that way we have clean books, clean separation, and if you skip the step, everything else gets messy at tax time. The second thing we did was implement an accountable plan. This lets his LLC reimburse him taxfree for things he's already paying for personally. So things like home office, internet, phone, mileage, so easily worth about $2,000 per year and 100% deductible. The third thing we did was leverage the Augusta rule. The LLC rents his personal residence for 14 days per year to host legitimate business activities like content planning, marketing strategy, etc. And about $500 per day, that's $7,000 deposited into his personal account completely taxfree. Then we're going to start tracking his net profit.
2:05 So once the LLC shows $40,000 plus in profit, we're going to file form 2553 and elect escorp status for January 1st of 2026. The escorp lets Mark split income between salary and profit distributions. And distributions aren't subject to self-employment tax. So, if he makes $40,000 in profit, pays himself $20,000 salary, and takes $20,000 in distributions, he avoids about $6,000 in payroll tax. The structure alone unlocks multiple deduction buckets and sets the stage for retirement account contributions, medical reimbursements, and more. Now, if you're watching this and thinking, okay, how much of this actually applies to me? I'm walking through all these frameworks step by step in a live master class this week. I'm going to drop the link in the description. Seats are limited, so register now and bring your questions. Next, we went after fast, scalable cash flow without needing to buy property. We walk Mark through Airbnb arbitrage and here's how it works. He finds a property to lease longterm. He furnishes it and then relists it on Airbnb at a nightly rate. He keeps a difference after rents, cleaning, and utilities. His goal is to launch two to three units this year.
3:00 He's going to make anywhere from $1,200 to $2,400 per month in net profit per unit. That means $3,600 to $7,200 total. So, his ideal profit is going to be $40,000 by Q4. And that's enough to justify the escorp election. And then he's going to fund it through a tapping into his helock or he's going to use 0% interest cards for the initial setup. typically anywhere from 6 to $7,000 per unit for furnishings, locks, photos, etc. Launching the first unit is going to take around 10 to 12 hours per week for the first month. And then after that, automation is going to kick in. We're going to leverage smart pricing tools, clear notifications, automated guest messaging, etc. After that, he's only going to need anywhere from 2 to 4 hours per week to manage everything ongoing. Now, once Mark starts generating business income, we immediately open up a solo 401k. And here's the math. You can contribute up to $23,500 per employee contribution plus 25% of profit as an employer. match. So, the total limit is about $69,000 if he maxes both. We're going to start small first.
3:52 Whatever he puts in is taxdeductible and grows tax deferred. In addition, we're going to execute a backdoor Roth IRA every year. This where $7,000 goes in non-deductible. It immediately gets converted and then grows 100% taxree. And down the road, if his profits go over $150,000, we're going to start layering in a cash balance plan to shelter another $100,000. Now, we also orange pill Mark into becoming a Bitcoiner. We don't believe in just blind diversification. We believe in understanding asymmetric upside and Bitcoin offers exactly that. The goal here is to allocate 80% of his investable capital into Bitcoin. He's going to do weekly buys and then once a month he's going to move funds to coal storage for security and he's going to keep 20% of investable capital into broad index fund ETFs like VTI or VO. Mark also owns a primary residence and has extra space. So we recommended to add an ADU conversion. So here's what that means. He's going to pull $25,000 from his helog to renovate the basement into a separate Airbnb unit. And that unit is going to bring in anywhere from $200 to $3,000 per month. So after all expenses, he's going to net anywhere from $1,500 to $2,000 per month. But here's the real kicker. Because it's a short-term rental and he materially participates, he's going to log 100 plus hours per year and more time than anyone else. And now he's going to be able to deduct up to $25,000 in rental losses against his W2 income. He also gets to claim 40% bonus depreciation in 2025.
5:04 And he combines that with a partial cost egg. And he's on track for a $7,500 refund from just that project. All this while adding value to his home and generating new income. Now, you don't build wealth without protecting it. Here are the asset protection layers that we walk through. First is a revocable living trust. It's going to avoid probate and assets pass seamlessly. The second is an umbrella policy. There's going to be $2 million in coverage and it's going to add protection beyond auto and home. And the third strategy is we're going to get series LLC's. Every future property he acquires gets its own LLC for isolation. Setup is super straightforward, but without these, one lawsuit could put everything at risk. Now, some of these are super time-sensitive, including bonus depreciation, which drops to 20% by 2027, unless it's reversed by Congress. You only get to max out your solo 401k if you open it before year end. And he locks in 0% credit offers don't last forever, especially in rising rate environments. So, what I want to do now is break down what year 1 looks like for him. First, for the escort FICA savings, he's going to save $6,000. The solar 401k deductions adds up to $12,000. The Augusta rule plus the accountable plan, $8,000. The ADU depreciation refund is $7,500. From Bitcoin plus the ETF growth is a conservative $10,000. In total, he's going to have $43,500 added to his net worth, but more importantly, he now has durable income streams, better tax positioning, and real control over his future. If you're wondering what's possible for your specific situation, you can join us on the upcoming live master class. We're
6:21 going to go deeper on these exact strategies with real numbers, take live questions, and also help you map out your next steps clearly. I'm going to put the link in the description. And again, spots are limited, so if you want to sign up, make sure you do that as soon as possible. Now, let me know in the comments what part of the strategy resonated with you the most or want me to make a more in-depth video about. And if you got value from this, please like and subscribe.
Learn the tax strategies with Preston
Preston teaches these strategies in a free live masterclass for high earners and business owners.